NHG Property Valuation Requirements: A Practical 2026 Guide
Check the 2026 NHG property valuation requirements for a Dutch home mortgage, including method, LTV, independence, validation, report age and energy measures.
When this valuation matters
If you need an NHG valuation, check method, loan-to-value, value after improvements, report age and property exceptions before ordering. Buyers, advisers, lenders and appraisers can check method, loan-to-value, value after improvements, report age and property exceptions before ordering.
TL;DR
Start with the current NHG conditions and the lender’s own acceptance rules. They can determine whether the file needs a physical, hybrid or validated report and whether a planned improvement or unusual property takes it outside that method.
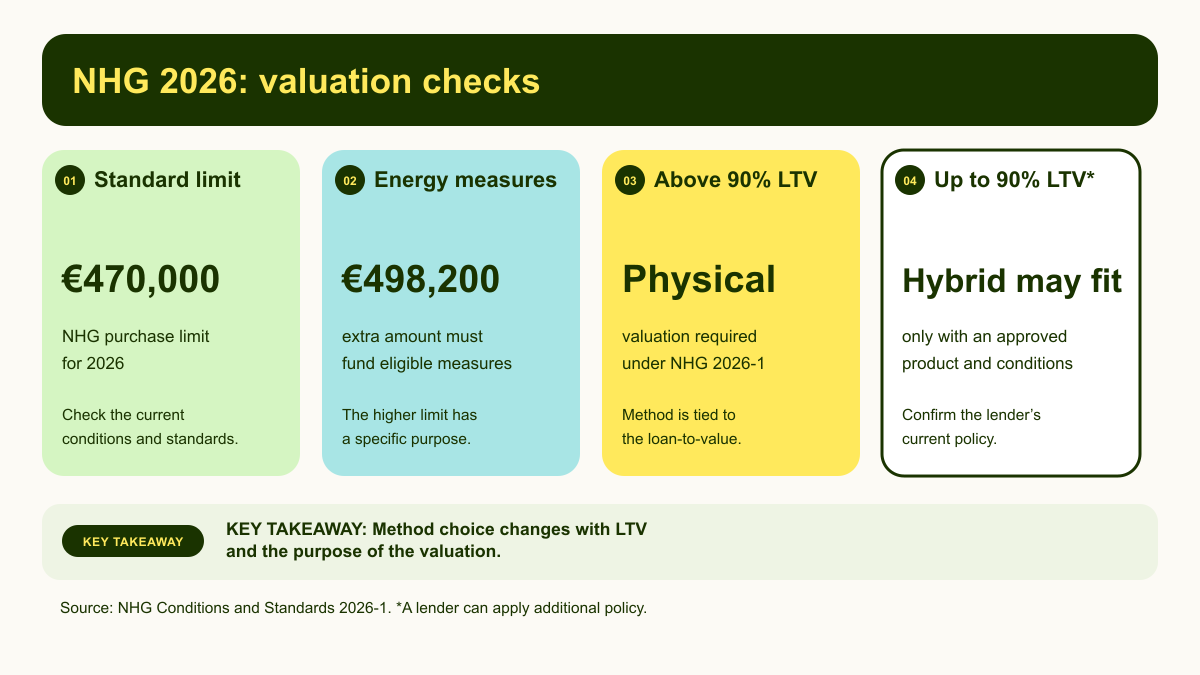
The 2026 NHG limit is €470,000. When qualifying energy-saving provisions are financed, the limit can reach €498,200 and the amount above €470,000 must fund those measures. NHG’s guarantee fee is 0.4% of the loan. Ask the lender to confirm the current product, report and timing conditions before you order.
Before you place the order, separate NWWI validation from NHG’s own acceptance conditions so you know which questions belong to the validation institute and which belong to the lender.
Keep that purpose in view as the details come in; each one matters because it changes what the appraiser needs to test.
NHG conditions sit within a wider lender file, so answer mortgage valuation questions about purpose, recipient and accepted method before you submit the report.
The 2026 figures
NHG announced these 2026 amounts:
- standard NHG limit: €470,000;
- limit with qualifying energy-saving provisions: €498,200;
- one-time guarantee fee: 0.4% of the loan amount.
The energy-related increase is conditional. NHG says the amount above €470,000 must be spent fully on qualifying energy-saving provisions through the relevant budget or provision rules. A home with an A++++ label can have additional conditions.
Here is the arithmetic when the full limit is used as the loan amount:
- €470,000 × 0.004 = €1,880;
- €498,200 × 0.004 = €1,992.80.
These are calculations on the published limits. They do not say what a buyer can borrow, whether the full limit applies or which other costs belong in the mortgage.
When NHG requires a physical valuation
The NHG Conditions and Standards 2026-1 state that a physical valuation is required in several situations, including:
- borrowing more than 90% of the market value;
- determining the value after quality improvements or energy-saving provisions;
- determining value after buying out a ground lease or obtaining full ownership;
- a forced private sale or foreclosure sale where residual-debt risk exists;
- buying a home at auction.
These conditions are attached to the purpose and the valuation date. A lender can ask for a physical report in additional situations. Mortgage valuation report requirements identify the questions that belong in a quote request.
When a hybrid valuation can apply
NHG describes hybrid valuation as a model-based value that a valuer reviews and approves at a distance. Its public valuation page allows hybrid valuation in selected purchase, refinancing and improvement situations. The mortgage may be no more than 90% of market value in those cases. A physical report is still needed for 100% financing under the NHG explanation.
Use only a product listed as permitted by NHG and accepted by the lender. A lower cost or quicker delivery does not change the rules. Confirm the product name, LTV ceiling and report channel in writing.
Online and physical valuation distinguishes what a hybrid label leaves outside a physical inspection. For the age calculation, valuation report validity separates the value date from the report and delivery dates.
Four requirements for a physical report
Independence
NHG says the appraiser must not have been involved in the purchase, sale, brokerage, building survey or financing of the home. The valuer must also have no ties to the buyer, seller or lender that compromise independence.
Accepted validation
An accepted validation institute must validate the report. The institute and report format must be acceptable under the current NHG and lender conditions. Keep that validation role separate from the lender’s acceptance decision.
Report age
NHG’s physical-report FAQ says the report may be no more than six months old, measured from the value date. The lender’s operational deadline can be shorter, so ask when the report must be delivered and used.
Complete value explanation
When the loan depends on a changed value after improvements, the report must show the current value, the adjustments and the value after the adjustments. A list of planned works without a value analysis may leave the report unable to answer the lender’s question.
Building condition and the 10% threshold
NHG’s 2026 conditions can require a building report when the valuer identifies direct maintenance costs that average more than 10% of the market value, when more building research is needed or when the building condition is poor. The valuer who prepares the valuation cannot also prepare the building report when NHG requires an objective separate report because of the conflict risk.
The 10% is a trigger in a particular NHG process, not a general rule that every home below the threshold is sound. Ask what the valuation says about condition and which separate inspection the lender wants.
Put those NHG checks in the same brief as the property facts so the valuer and lender are working from the same question.
These are the details worth checking before you compare providers or send the file.
A buyer’s NHG checklist
Before ordering, record:
- loan purpose: purchase, refinancing, improvement or another case;
- expected LTV and whether the loan is above 90% of value;
- current, improved or post-energy-measure value needed;
- physical or approved hybrid method;
- independence and validation conditions;
- value date, six-month age rule and delivery deadline;
- building-report trigger and separate inspection needs;
- the current NHG version and lender’s written answer.
Property valuation documents should cover drawings, permits, invoices, energy records and property information. If the loan includes planned improvement, renovation valuation separates current value from post-work value.
What changes for energy measures
NHG’s energy guidance permits up to €498,200 in 2026 when the extra amount is used for eligible energy-saving measures. The Energiebespaarbudget can finance up to 6% above the property value before the measures. When the measures and costs are known, the Energy-Saving Provisions option can finance up to 6% above the value after improvement, subject to the rules.
The valuation method matters here. NHG states that a physical valuation is needed when the value after energy-saving provisions is being determined. A hybrid product can have a 90% LTV limit. Ask the lender which method matches the planned works.
Keep the source current
NHG updates its Conditions and Standards. The cited requirements use the version marked 2026-1 and pages checked on 27 August 2026. A live application should use the version that governs the binding offer and the lender’s current instructions. Save the answer with the quote so the report provider receives the same brief.
Before the appointment, settle the practical questions that affect the report.
FAQ
Is a physical valuation always required for NHG?
No. NHG allows approved hybrid products in selected situations. Its public explanation sets a 90% LTV limit for those hybrid cases and keeps a physical report for 100% financing. The conditions, product list and lender policy decide the application.
How old can an NHG valuation report be?
NHG’s physical-report FAQ says no more than six months from the value date. The lender can impose an earlier delivery or use deadline.
Is the 0.4% NHG fee a valuation cost?
No. It is a separate one-time guarantee fee for the NHG mortgage. The calculations of €1,880 and €1,992.80 apply the fee to the published limits for illustration and do not include a valuation fee.
The thresholds and method conditions here belong to the stated 2026 NHG context. Confirm the current lender and NHG requirements before ordering, especially when age or improvements matter.
Ask about NHG requirements →